Autonomous Driving Market by Company
Discover the companies building self-driving technology and advanced driver assistance systems. Compare approaches from vision-only to lidar, and track the road to full autonomy.
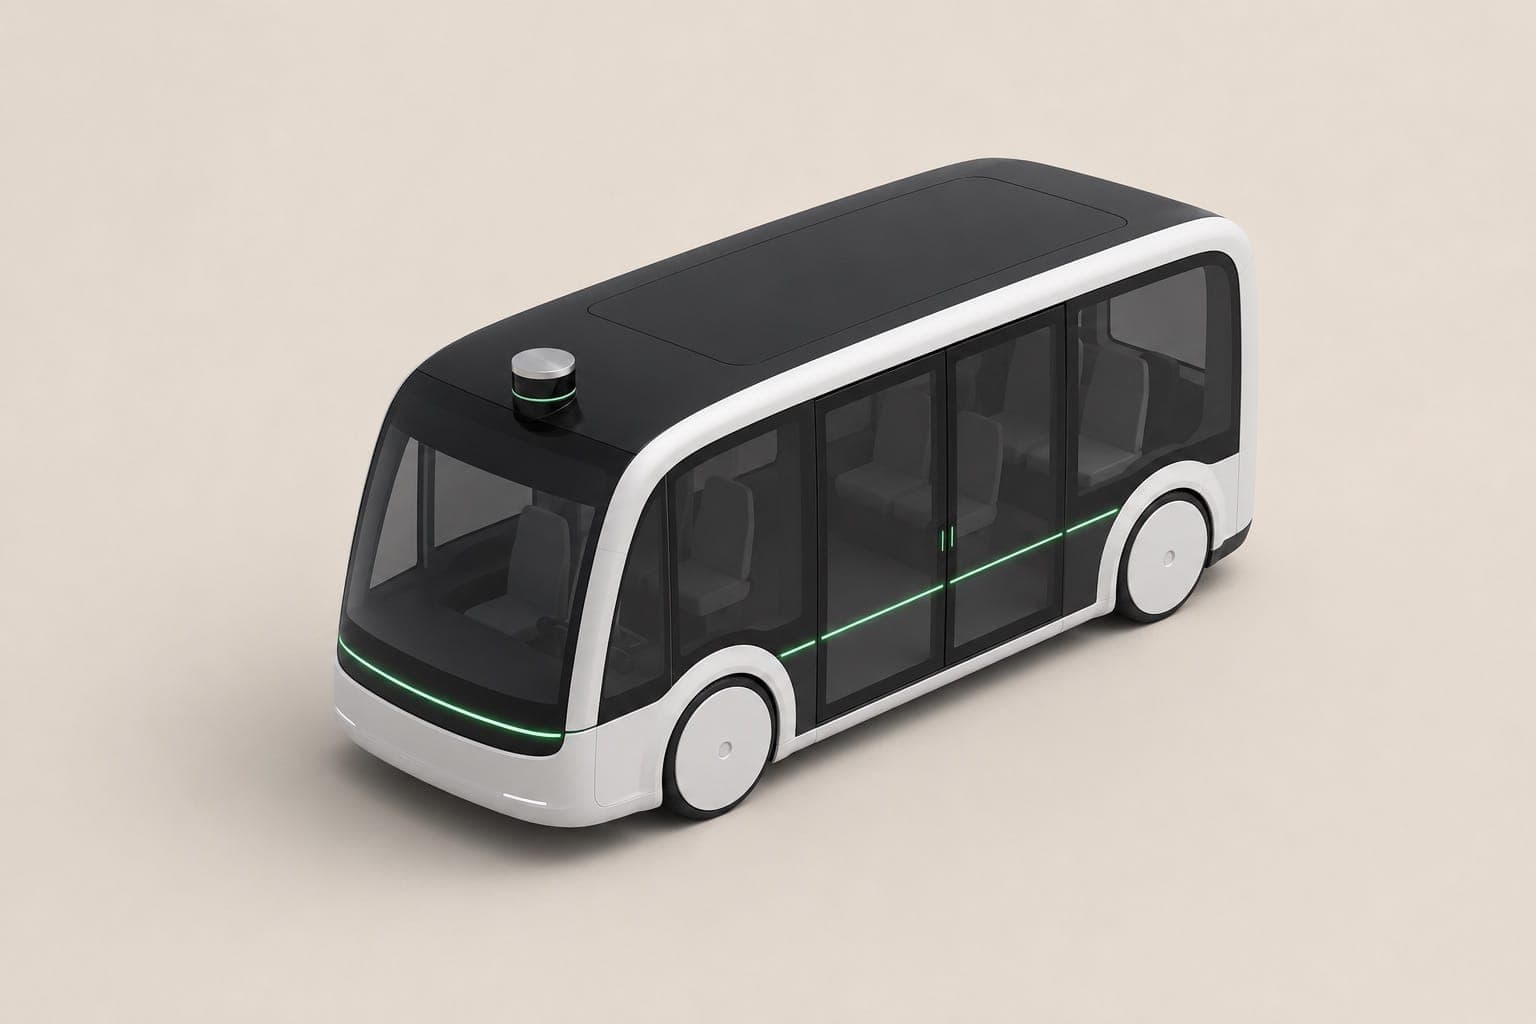
The Autonomy sector on Sterling tracks 28 companies, led by Mobileye (70%), NVIDIA Drive (15%), Qualcomm (8%) by market share.
Autonomy market share by company
| # | Company | Market share |
|---|---|---|
| 1 | MobileyeMBLY | 70% |
| 2 | NVIDIA DriveNVDA | 15% |
| 3 | QualcommQCOM | 8% |
| 4 | Others | 7% |
Robotaxi Companies by Fleet Size
| # | Company | Vehicles | As of |
|---|---|---|---|
| 1 | Waymo | 3,067 | 2025 |
| 2 | Baidu Apollo Go | 1,500 | 2025 |
| 3 | Pony.ai | 1,100 | 2025 |
| 4 | Tesla | 1,080 | 2026 |
| 5 | WeRide | 850 | 2025 |
| 6 | Zoox (Amazon) | 50 | 2025 |
Autonomous Driving Segments
Robotaxis
Companies building or operating driverless ride-hailing fleets, from dedicated robotaxi operators to platform partners.
Waymo (Alphabet)
Operates Waymo, the largest commercial robotaxi service in the U.S.
Baidu Apollo
Runs Apollo Go, China's largest robotaxi fleet across 10+ cities.
Tesla Robotaxi
Developing the Cybercab robotaxi and unsupervised FSD for its existing fleet.
Pony.ai
Deploys L4 robotaxis in Beijing, Shanghai, Shenzhen, and Guangzhou.
Zoox (Amazon)
Building Zoox, a purpose-built bidirectional robotaxi with no steering wheel.
Cruise (GM)
Restructuring Cruise from public robotaxis toward supervised autonomy in GM vehicles.
Uber
Partnering with Waymo and Aurora to deploy robotaxis on its rideshare network.
DiDi
Testing driverless vehicles in Shanghai to integrate AVs into its rideshare fleet.
ADAS / Consumer
Consumer-facing driver-assistance systems sold in production vehicles: from highway autopilot to city-level navigation.
Tesla FSD
Deploys vision-only FSD across 6M+ vehicles with the largest real-world driving dataset.
Mobileye
Supplies ADAS vision chips to 50+ automakers, powering 150M+ vehicles worldwide.
Intel (Mobileye parent)
Parent of Mobileye, providing manufacturing and strategic resources for ADAS development.
XPeng
Offers XNGP, one of China's most advanced city-level autonomous navigation systems.
NIO
Develops the NAD system with highway and city navigation for its premium EV lineup.
Li Auto
Deploys NOA across its SUV lineup, making city-level autonomy standard on all models.
BYD
Democratizing ADAS through in-house development and partnerships with Huawei and Momenta.
Lucid
Ships DreamDrive with 32 sensors including lidar, exploring robotaxi licensing.
Trucking & Logistics
Autonomous technology targeting freight corridors, last-mile delivery, and commercial fleet autonomy.
Aurora
Building the Aurora Driver for autonomous trucking on U.S. freight corridors with PACCAR.
Waymo (Alphabet)
Expanding Waymo Via for autonomous freight and last-mile delivery applications.
WeRide
Deploying L4 autonomy across minibuses, street sweepers, and logistics vehicles in 30+ cities.
Tesla Semi
Building the Semi with full FSD hardware: positioned to enter autonomous freight with its vision-based self-driving stack.
Hardware & Software
The compute chips, lidar sensors, and software platforms that power autonomous driving: from silicon to full-stack solutions.
Tesla FSD
Designs custom FSD chips and inference hardware in-house, paired with its own vision-only software stack.
NVIDIA
Designs the DRIVE Orin and Thor chips: the dominant high-performance compute for AV stacks.
Mobileye
Supplies EyeQ vision processors to 50+ automakers, powering 150M+ vehicles with ADAS.
Qualcomm
Develops Snapdragon Ride SoCs combining ADAS, cockpit, and connectivity on a single chip.
Luminar
Shipped Iris lidar into Volvo, Mercedes, and Polestar programs; Chapter 11 in December 2025, assets sold, equity cancelled.

Hesai
China's largest lidar maker, shipping AT128 and FT120 sensors to robotaxi fleets and automakers.

Aptiv
Tier-1 supplier providing wiring, radar, cameras, and ADAS integration to global OEMs.

Continental
Manufactures automotive radar, cameras, and ADAS ECUs at scale for dozens of OEMs worldwide.
Intel (Mobileye parent)
Parent of Mobileye, providing foundry and strategic resources for autonomous driving silicon.
AD Supply Chain: Who Does What
Maps each company onto the autonomous driving stack: from designing the silicon chips, to building sensors (lidar, cameras, radar), to writing the self-driving software, to operating the ride-hailing fleet.
TeslaWaymoNVIDIAMobileyeQualcommBaidu ApolloAuroraZooxHesaiLuminarPony.aiCruise (GM)WeRideDiDiUberIntel (Mobileye parent)AptivContinentalLucidNIOXPengLi AutoBYDTeslaWaymoNVIDIAMobileyeQualcommBaidu ApolloAuroraZooxHesaiLuminarPony.aiCruise (GM)WeRideDiDiUberIntel (Mobileye parent)AptivContinentalLucidNIOXPengLi AutoBYDCumulative Driverless Miles (L4)
L4 autonomy = fully self-driving within a defined area (geofenced city or route): no human driver needed inside the zone. Cumulative rider-only miles, driven with no human in the vehicle; supervised and safety-driver miles are not counted.
Autonomous Driving R&D Spending
Estimate, not company-reported: only Aurora is a reported R&D line. Waymo is Alphabet's Other Bets operating loss, Cruise is GM's Cruise EBIT-adjusted loss, and Tesla FSD (35%) and Baidu Apollo (20%) are assumed shares of total R&D. Annual dollars each company puts into self-driving, in $B.
Regulatory Permits by Company & Region
Where each self-driving company is legally allowed to operate, tracking the permits behind robotaxi and AV deployment across the US, China, and other regions.
- active
Waymo in California
Driverless Deployment · 2023-08
Notes
The CPUC approved fared driverless passenger service in San Francisco at any time on 10 Aug 2023, on top of the DMV deployment permit Waymo already held (CPUC press release, 10 Aug 2023). The CPUC permit list shows a Driverless Deployment permit with operating-domain maps for Northern and Southern California
- active
Waymo in Arizona
No permit (state law) · 2020-10
Notes
Phoenix metro. Arizona issues no permit for driverless operation. A.R.S. 28-9702 lets a fully autonomous vehicle run without a human driver once the operator files a law enforcement interaction plan with ADOT and the Department of Public Safety and a written statement with ADOT (Arizona Legislature, A.R.S. 28-9702). Its text counts a 60-day filing deadline from 29 Sep 2021 for operators already running, so it postdates Waymo's launch. Granted is when Waymo opened its fully driverless service to the general public in Phoenix, 8 Oct 2020 (Waymo blog, 8 Oct 2020). Waymo introduced its paid Waymo One service there on 5 Dec 2018 with drivers aboard (Waymo blog, 5 Dec 2018)
- active
Waymo in Texas
No permit until 2026 (state law) · 2024-03
Notes
Austin metro. Texas required no permit under SB 2205 (2017), so Waymo began driverless operations without one. SB 2807 (2025) now requires a TxDMV authorization, enforceable from 28 May 2026, and Waymo LLC is on the TxDMV authorization list of 29 Oct 2026 with 1,259 vehicles (grant date not published). Granted is when Waymo said it had started rider-only testing in Austin (Waymo blog, 13 Mar 2024)
- active
Waymo in Georgia
No permit (state law) · 2025-06
Notes
Atlanta metro. Georgia SB 219 (Act 214, effective 1 Jul 2017, O.C.G.A. 40-8-11) lets a vehicle operate without a driver if it meets registration, insurance and equipment rules, so no permit is needed (Georgia General Assembly 2017 session summary). Granted is when Waymo and Uber began public fully autonomous rides in Atlanta, 24 Jun 2025 (Uber news release); Waymo's own posts give no earlier driverless start date
- active
Tesla in California
Charter-Party (TCP) · 2025-03
Notes
Charter-party carrier (TCP) permit, the same type a limousine company holds, requiring a human driver. CPUC confirmed Tesla is NOT authorized to transport the public in an autonomous vehicle
- active
Tesla in Texas
Robotaxi Commercial · 2025-06
Notes
Robotaxi launch in Austin. Texas required no permit at launch (SB 2205, 2017). SB 2807 (2025) now requires a TxDMV authorization, enforceable from 28 May 2026, and Tesla Robotaxi, LLC is on the TxDMV authorization list of 29 Oct 2026 with 1,080 vehicles (grant date not published)
- active
Tesla in Nevada
AVNC Permit 002 · 2026-07-27
Notes
Tesla Robotaxi LLC, docket 26-05015. Interim order 2026-07-27 capped the fleet at 10. On 2026-08-20 all three NTA commissioners unanimously approved the docket for 5,000 fully autonomous vehicles in Las Vegas. Passenger service not started.
- active
Waymo in Nevada
AVNC · 2026-08-20
Notes
Docket 26-06007. Approved unanimously by all three NTA commissioners on 2026-08-20, same vote as Tesla's Las Vegas docket.
- suspended
Cruise (GM) in California
Driverless Deployment · 2022-06
Notes
The DMV issued Cruise's deployment permit in September 2021 (GM Form 10-K for 2021), and the CPUC issued Cruise's Driverless Deployment permit on 2 Jun 2022, allowing fares for rides with no safety driver (CPUC press release, 2 Jun 2022). The DMV suspended Cruise's deployment and driverless testing permits with immediate effect on 24 Oct 2023 (suspended, not revoked) and left its permit for testing with a safety driver unaffected (California DMV statement, 24 Oct 2023). The DMV and CPUC permit lists of October 2026 no longer include Cruise
- active
Zoox (Amazon) in California
Driverless Pilot · 2023-12
Notes
Driverless testing and pilot operations in Foster City and Las Vegas
- active
Zoox (Amazon) in United States (federal)
Part 555 Commercial Exemption · 2026-07
Notes
NHTSA decision issued 28 Jul 2026 for a purpose-built robotaxi without manual controls, effective 31 Jul 2026 to 31 Jul 2028, up to 2,500 vehicles per 12 months; Zoox calls it the first-ever commercial exemption (Federal Register, 31 Jul 2026; Zoox journal, 30 Jul 2026). Federal approval to charge fares; Zoox still has to meet Nevada and California commercial requirements
- active
Aurora in California
Testing (with a driver)
Notes
Aurora Operations, Inc. is on the DMV list of Autonomous Vehicle Testing Permit holders with a driver, dated 23 Oct 2026, which gives no grant date (California DMV permit holder page). Aurora is not on the CPUC permits-issued list (CPUC, accessed 31 Oct 2026), so the earlier CPUC Drivered Pilot entry for 2023-09 had no support and was removed. Aurora said California regulation currently permits testing and deployment of autonomous light-duty vehicles only, and that state regulators released proposed rules for autonomous trucks in 2025 (Aurora Form 10-K for 2025, filed 11 Feb 2026)
- active
Aurora in Texas
Driverless Commercial (Trucking) · 2025-04
Notes
Aurora said it launched driverless commercial operations in April 2025 (Aurora Form 10-K for 2025, filed 11 Feb 2026), with regular driverless hauls between Dallas and Houston (Aurora Form 8-K, 1 May 2025). Texas required no permit at launch (SB 2205, 2017). Aurora Operations is on the TxDMV authorization list of 29 Oct 2026 with 91 vehicles (SB 2807, enforceable from 28 May 2026)
- active
Baidu Apollo in Beijing
Fully Driverless Commercial · 2022-07
Notes
First fully driverless commercial permit in China; Yizhuang district
- active
Baidu Apollo in Wuhan
Fully Driverless Commercial · 2022-08
Notes
Largest driverless commercial area in China; 500+ sq km
- active
Baidu Apollo in Chongqing
Fully Driverless Commercial · 2022-08
Notes
Concurrent approval with Wuhan for fully driverless rides
- active
Pony.ai in Beijing
Fully Driverless Commercial · 2023-08
Notes
Pony.ai said it was granted permission in August 2023 to offer public-facing fare-charging robotaxi services without safety drivers in Beijing (Pony AI Form 424B4, filed 27 Nov 2024)
- active
Pony.ai in Shanghai
Driverless Commercial · 2025-07
Notes
Pony.ai said it was among the first in China to obtain licenses to operate fully driverless robotaxis in all four Tier-1 cities, and already held permission for public-facing robotaxi services in Shanghai at its November 2024 IPO (Pony AI Form 424B4, filed 27 Nov 2024). Pony.ai said it received a permit for fully driverless commercial robotaxi services in Shanghai's Pudong New Area in July 2025 (Pony AI Form 20-F for 2025, filed 22 Apr 2026)
- active
Pony.ai in Guangzhou
Fully Driverless Commercial · 2023-12
Notes
Pony.ai lists December 2023 as when it became the first to receive a permit for fare-charging, fully driverless robotaxi service in Guangzhou (Pony.ai company timeline). It also said it later obtained permission for fully driverless public-facing fare-charging robotaxi services in Guangzhou and Shenzhen, after the August 2023 Beijing permission (Pony AI Form 424B4, filed 27 Nov 2024)
- active
WeRide in Guangzhou
Online Ride-Hailing License · 2021
Notes
WeRide's Form 424B4 (filed 25 Oct 2024) credits the grant of the permit for ride-hailing operation with the rise in its share value between 31 Dec 2020 and 31 Mar 2021, and says the online ride hailing license for the WeRide Go app is held by Guangzhou Jingqi. No month is published. WeRide unveiled China's first publicly accessible paid robotaxi service in downtown Guangzhou in November 2019 (same filing)
- active
WeRide in Abu Dhabi, UAE
Fully Driverless Commercial · 2025-10
Notes
WeRide said a permit for fully driverless robotaxi commercial operations in Abu Dhabi was granted on 31 Oct 2025, with no safety officer in the vehicle (WeRide news release, 17 Nov 2025; WeRide Form 20-F for 2025, filed 23 Apr 2026). The Integrated Transport Centre (Abu Dhabi Mobility) said on 13 Nov 2025 it had granted the first two operating permits for commercial fully autonomous vehicles, with WeRide (with Uber and Tawasul) and AutoGo-K2 as the phase one operators (Abu Dhabi Media Office, 13 Nov 2025). WeRide also said it was granted the UAE's first and only national license for self-driving vehicles in August 2023, to test on public roads across the entire country (WeRide Form 424B4, filed 25 Oct 2024)
- active
WeRide in California
Drivered + Driverless Pilot · 2024-08
Notes
WeRide holds California DMV permits to test in San Jose without a human driver onboard and a permit, obtained in August 2024, to carry passengers in testing vehicles with no fares and no rides for the general public (WeRide Form 424B4, filed 25 Oct 2024). The CPUC permit list of October 2026 shows WeRide AI with Drivered Pilot and Driverless Pilot permits. The CPUC issued WeRide Corp. a Class P charter-party permit (TCP0045411-P) on 2 Aug 2024 for the Drivered and Driverless Autonomous Vehicle Passenger Service Pilot Programs (CPUC permit, 2 Aug 2024)
WaymoWaymoWaymoWaymoTeslaTeslaTeslaWaymoCruise (GM)Zoox (Amazon)Zoox (Amazon)AuroraAuroraBaidu ApolloBaidu ApolloBaidu ApolloPony.aiPony.aiPony.aiWeRideWeRideWeRidePaid Driverless Miles vs Supervised ADAS Miles
Waymo rider-only miles are Waymo-disclosed fully driverless service miles. Tesla FSD miles are Tesla's own Supervised counter (Tesla claim, SAE Level 2). Tesla has not disclosed paid robotaxi miles. Log scale because Tesla's claimed FSD miles dwarf disclosed driverless service miles.
CA DMV Autonomous Test Miles (Safety Driver vs Driverless)
California tester miles reported to DMV, not global company-claimed L4 totals. Waymo led safety-driver miles. Cruise led CA driverless miles in 2023, then lost the driverless permit. Tesla FSD customer miles are not in this program.
Companies in the Autonomy sector (28)
Related industries
Frequently asked questions
What is the Autonomy sector?
Discover the companies building self-driving technology and advanced driver assistance systems. Compare approaches from vision-only to lidar, and track the road to full autonomy.
Which companies lead the Autonomy sector?
Sterling tracks 28 companies in Autonomy, led by Mobileye (70%), NVIDIA Drive (15%) and Qualcomm (8%).
How can I invest in the Autonomy sector?
Publicly traded names in Autonomy include Tesla FSD (TSLA), Waymo (Alphabet), Cruise (GM), Mobileye (MBLY) and Aurora (AUR). Compare them side by side on Sterling. Data last updated November 7, 2026.